Research-based product playbook · Published May 11, 2026 · How we research
10 min read · Fact-checked November 4, 2026 · Research-based analysis
THE EDITORIAL VIEW
Production reconciliation explains how opening material, receipts, consumption, acceptable output and losses relate. It gives purchasing and sales a basis for the next decision. A dashboard total is helpful only when the team can investigate the movement behind it and distinguish a genuine operational variance from a unit or timing error.
Best fit: An assembled-goods brand reconciling a week of material receipts and production jobs.
Poor fit: An unverified configuration or an undefined completion event for this specific task.
Table of Contents
Production reconciliation explains how opening material, receipts, consumption, acceptable output and losses relate. It gives purchasing and sales a basis for the next decision. A dashboard total is helpful only when the team can investigate the movement behind it and distinguish a genuine operational variance from a unit or timing error.
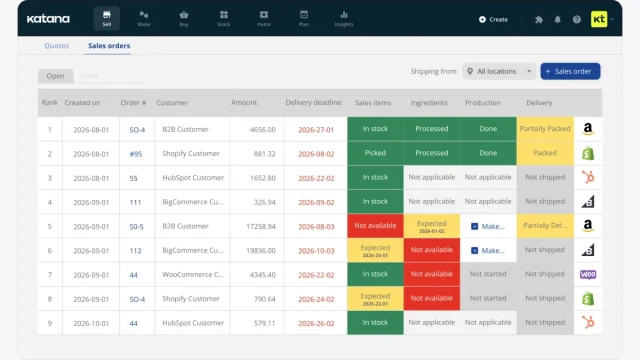
This fictional assembled-goods brand is evaluating Katana across a normal production week. Some jobs complete in stages, a supplier delivery differs from the purchase expectation and one component is rejected. The brand needs a repeatable review that leaves the next stock and purchasing action owned.
Katana’s current pricing and contract arrangement should be confirmed from the actual scope. The main guide discusses the Advantage contract and relevant implementation boundaries. The financial examples here use hypothetical arrangements to explain operating cost; they are not Katana quotes or observed manufacturing results.
Design the work around the actual completion event
1. Reconcile opening quantities in the correct units
Establish the starting date, storage locations and item units for the review. Keep counted stock, expected receipts and committed material distinguishable.
A review can begin with a mixture of physical availability and future supply that never represented one real stock position.
2. Compare receipt evidence with the purchase expectation
Record received quantity, accepted quantity and the treatment of damaged or missing material. Keep supplier and purchase references available for follow-up.
A delivery can be marked received even though part of its quantity cannot enter usable stock.
3. Follow partial jobs without pretending they are finished
Define how the intended configuration records work completed, material consumed and output still awaiting an action. Preserve the job reference across stages.
A partly completed job can disappear from planning if its status is treated as the whole quantity’s availability.
4. Classify variances before changing a quantity
Separate unit errors, recording timing, actual scrap and a different recipe requirement. Assign the investigation to someone able to verify the relevant evidence.
A stock adjustment can make totals agree while concealing a recurring production or master-data problem.
5. Include investigation in the operating budget
Measure ordinary review and exceptional repair separately. Estimate the recurring work required to maintain items, recipes and job records at the intended volume.
A software comparison can omit the planner effort needed to keep its data meaningful.
6. Close the review with next purchasing decisions
Translate the reconciled position into owned reorder, schedule or customer actions. Keep a review note for decisions deferred pending supplier or production evidence.
A correct historical report can still fail to change the next shortage or repeated recording error.
Build a complete cost model with a consistent unit
The following comparison is a fictional purchasing exercise for an assembled-goods brand reconciling a week of material receipts and production jobs. Arrangement A and arrangement B are hypothetical configurations, not named Katana plans or current vendor prices. Their purpose is to expose a fixed-cost versus workload tradeoff. Replace every amount with the provider quote and the team’s observed work before making a purchasing decision.
Assume 300 attempted reconciled production jobs in one review period. Arrangement A has $140 of allocated fixed cost and $1.20 of variable cost per attempt. Arrangement B has $320 of fixed cost and $0.60 per attempt. Both also require an assumed 9 hours of operating work at $50 per hour. That shared labor amount is $450. Keeping it visible prevents a subscription comparison from being mistaken for the complete cost of running the process.
| Cost component | Arrangement A | Arrangement B |
|---|---|---|
| Allocated fixed amount | $140 | $320 |
| Attempted workload | 300 | 300 |
| Variable amount per attempt | $1.20 | $0.60 |
| Variable subtotal | $360.00 | $180.00 |
| Assumed operating labor | $450 | $450 |
| Scoped total | $950.00 | $950.00 |
Under these inputs, the lower scoped total is a tie. The arithmetic does not establish functional equivalence. If one arrangement cannot produce an accepted reconciled production job, its lower price does not purchase the same outcome. First establish that the relevant permissions, product functions and receiving workflow satisfy the requirement. Then compare the cost of the arrangements that remain eligible.
Calculate the crossover instead of choosing from one sample month
Ignoring the shared labor that is identical in this example, set the two totals equal: 140 + 1.20 × volume = 320 + 0.60 × volume. The difference in fixed amounts is $180; the variable difference is $0.60 per attempt. The crossover is therefore 300 attempts. Below that level A has the lower modeled platform allocation; above it B does, assuming the same definitions and the same quality of output.
For Katana, inspect the current contract, item model and implementation scope rather than an obsolete fixed-price comparison. A SKU, component movement and supported finished-product commitment describe different parts of manufacturing work. Include unit mapping and the recurring review needed to keep the model reliable. The 300 attempted reconciled production jobs in this example are an internal operating measure. Translate them into the confirmed purchased units before replacing the hypothetical costs. A minimum commitment, annual term or tier boundary may require a different model; retain the current quote with its actual scope.
Divide by accepted output as well as attempted work
Suppose 240 of the 300 attempts meet the agreed completion criteria. This invented usable-output share is 80%; it is not a Katana success rate. Arrangement A would cost $3.96 per approved reconciled production job, while B would cost $3.96. Dividing by all attempts instead would give $3.17 and $3.17. Both calculations are arithmetically valid, but only the first answers the question about accepted operating output.
Explain what happened to the remaining 60 cases. Some may be inappropriate inputs; others may need a correction or an unavailable decision. Do not describe them all as software failures. Equally, do not erase their inspection cost from the comparison. A useful review separates input quality, the configuration’s behavior and the receiving team’s ability to continue the work. Each requires a different response.
Include switching effort and the cost of carrying an exception
A new arrangement may require preparation, record cleanup, template work or training. If a controlled estimate adds twelve hours at the same $50 rate, that is $600 of transition labor. State whether it is a one-time investment and over what period you intend to recover it. Do not treat it as a monthly fee indefinitely or disappear it from the decision merely because an existing employee performs the work.
Now vary the exception burden. Adding four hours of review increases either arrangement by $200. That can be more consequential than a small difference in the quoted fee. The practical question is which input or handoff creates those hours and whether the proposed configuration removes them. A larger allowance that leaves the repair process untouched may increase throughput without making the work more economical.
For an assembled-goods brand reconciling a week of material receipts and production jobs, compare quiet, expected and spike periods using the same reconciled production job definition. The modeled 300 attempts are only one workload. A changed package boundary or approval burden can alter the comparison, so retain a range where the work is uncertain. Link the commitment to the actual requirement and review point rather than treating the spreadsheet’s decimal places as evidence that future demand is known.
Test the six assumptions that could change this budget
The following exercises connect the financial model to the actual Katana workflow. Keep input definitions, the selected configuration and the person responsible for each decision beside the observed result. A provider demonstration can establish an available route; it does not replace the team’s own acceptance of the business meaning or the ongoing work required to maintain it.
Exercise 1: Reconcile opening quantities in the correct units
Inspect a controlled material held in two locations and one purchase delivery still in transit.
The opening position has a defined boundary and the team knows what it excludes. Record the input reference, the observed result and the responsible next operator. If the result depends on a manual convention, retain that convention with this exercise so the next person can repeat it.
Exercise 2: Compare receipt evidence with the purchase expectation
Use a controlled receipt with a short quantity and a rejected component.
The usable stock and the supplier follow-up reflect the same accepted physical result. Record the input reference, the observed result and the responsible next operator. If the result depends on a manual convention, retain that convention with this exercise so the next person can repeat it.
Exercise 3: Follow partial jobs without pretending they are finished
Reconcile a controlled job with only part of the intended output accepted.
The next planner can distinguish usable output from the unfinished commitment. Record the input reference, the observed result and the responsible next operator. If the result depends on a manual convention, retain that convention with this exercise so the next person can repeat it.
Exercise 4: Classify variances before changing a quantity
Inspect a controlled difference caused by a unit mismatch and another caused by genuine rejected material.
Each difference has a reason, an approved treatment and an owner for any corrective action. Record the input reference, the observed result and the responsible next operator. If the result depends on a manual convention, retain that convention with this exercise so the next person can repeat it.
Exercise 5: Include investigation in the operating budget
Cost one clean job and one job whose receipt or consumption requires investigation.
The estimate reaches a reconciled job and includes the work outside the normal path. Record the input reference, the observed result and the responsible next operator. If the result depends on a manual convention, retain that convention with this exercise so the next person can repeat it.
Exercise 6: Close the review with next purchasing decisions
Ask a covering planner to continue from the review note without the original analyst.
They can identify the accepted stock position and the next decisions requiring action. Record the input reference, the observed result and the responsible next operator. If the result depends on a manual convention, retain that convention with this exercise so the next person can repeat it.
Keep an operating record someone else can continue
For an assembled-goods brand reconciling a week of material receipts and production jobs, keep one reference for each reconciled production job. Use that reference across the input, the accepted result and any exception record. It allows a reviewer to follow the work without relying on a customer’s name, a screenshot title or the memory of the person who first handled it. Where the destination system assigns its own identifier, retain both references and explain the relationship.
| Record field | What to put in it | Why it belongs in this workflow |
|---|---|---|
| Input reference | The original request, item or approved brief | Connects the result to the actual starting point |
| Configuration version | The relevant rule, template or account arrangement | Makes an observed result reproducible |
| Completion evidence | What establishes an accepted reconciled production job | Keeps the outcome definition stable |
| Exception reason | The missing fact, conflict or failed requirement | Directs repair toward the cause |
| Current owner | The person or queue that accepted the next action | Makes continuation visible |
| Review point | When the case or configuration needs another decision | Prevents unfinished work from disappearing |
For one reconciled production job, write what the evidence establishes before proposing an explanation. In an assembled-goods brand reconciling a week of material receipts and production jobs, the note needs the starting reference and the accepted next responsibility as well as a visible result. Keep the supporting source small enough to inspect. A large screenshot collection should not replace an explicit decision about this particular outcome.
Before increasing the workload for an assembled-goods brand reconciling a week of material receipts and production jobs, review the held reconciled production jobs by their actual cause. Use the six exercises to locate an input, configuration or responsibility gap, then repeat the affected route after its repair. The first ordinary reconciled production job does not establish that a different unresolved case has become acceptable.
Make the next decision from the evidence
Keep the review bounded enough to run consistently and detailed enough to explain consequential differences. A recurring unexplained variance is a reason to investigate its cause rather than to normalize an adjustment routine. Use the evidence to improve material, recipe and receipt discipline.
Compare Katana’s complete arrangement with the operational work it supports. A higher level of stock visibility is valuable when it leads to credible production and purchasing decisions. Include the implementation and recurring review effort needed to sustain that visibility.
Keep a short decision note for this specific Katana use case: the work approved, the conditions still outstanding, the owner of each outstanding decision and the next review date. A conditional approval is useful when its boundaries are visible. It becomes misleading when an unresolved requirement is presented as an observed capability.
More Katana guides
- Katana: connect stock availability with the production promise
- Katana bills of materials: check component availability before promising finished stock
Keep exploring
Sources and editorial notes
Official product sources checked November 4, 2026. This is research-based editorial analysis with a proposed operating workbook. The scenarios, workload numbers and hypothetical financial arrangements are invented planning inputs, not observed product performance or vendor quotations. Confirm the current plan, account and regional requirements before purchasing. We have not performed a hands-on product test.
Product buttons lead directly to the official provider. Affiliate disclosure · Editorial methodology.